Refinancing makes sense when the money you save each month pays back your closing costs well before you expect to sell or pay off the home, and when the new loan does not quietly add years of interest by restarting a 30-year clock. There is no universal “rate must drop by X” rule; the answer comes from a short break-even calculation with your own numbers. Refinancing is usually a bad idea when you might move soon, when closing costs are high relative to the savings, or when the main appeal is a lower payment that comes from a longer term rather than a lower rate.
Key takeaways
- Break-even month = closing costs ÷ monthly savings. If you will not stay in the home well past that month, skip the refinance.
- A new 30-year loan lowers the payment partly by stretching the term. In our example it saves $152.75 a month but adds $30,263.47 of lifetime interest.
- Matching the new term to the years you have left, or keeping your old payment, turns a small rate cut into real interest savings.
- Get at least three Loan Estimates for the same loan type and compare the closing-cost totals, not just the rate.
- FHA and VA borrowers have streamlined options, and FHA borrowers with enough equity may drop mortgage insurance by moving to a conventional loan.
The break-even test, worked with real numbers
Here is an example household. In late October 2023 they took a 30-year fixed loan at 7.79%, which was the Freddie Mac Primary Mortgage Market Survey (PMMS) 30-year average for the week of October 26, 2023. After 36 payments they owe $320,000.00, pay $2,368.37 a month in principal and interest, and have 27 years (324 payments) left.
As of the week of October 15, 2026, the PMMS 30-year fixed average is 7.40% and the 15-year average is 6.71%. PMMS reflects borrowers with strong credit and 20% down, so your own quote may be higher or lower. Rates rose sharply in September and October 2026, which is why the gap in this example is small.
A new 30-year loan for $320,000 at 7.40% has a payment of $2,215.62, a saving of $152.75 a month. Freddie Mac’s consumer site says to expect refinance closing costs of 3% to 6% of the loan principal, so we ran three scenarios: 2% (a low-cost or heavily negotiated deal), 3% and 5%. All figures below are EarlyPayoff calculations and cover principal and interest only.
| Closing costs | Dollar cost | Monthly saving | Months to break even | Years (approx.) |
|---|---|---|---|---|
| 2% of loan | $6,400.00 | $152.75 | 42 | 3.5 |
| 3% of loan | $9,600.00 | $152.75 | 63 | 5.2 |
| 5% of loan | $16,000.00 | $152.75 | 105 | 8.8 |
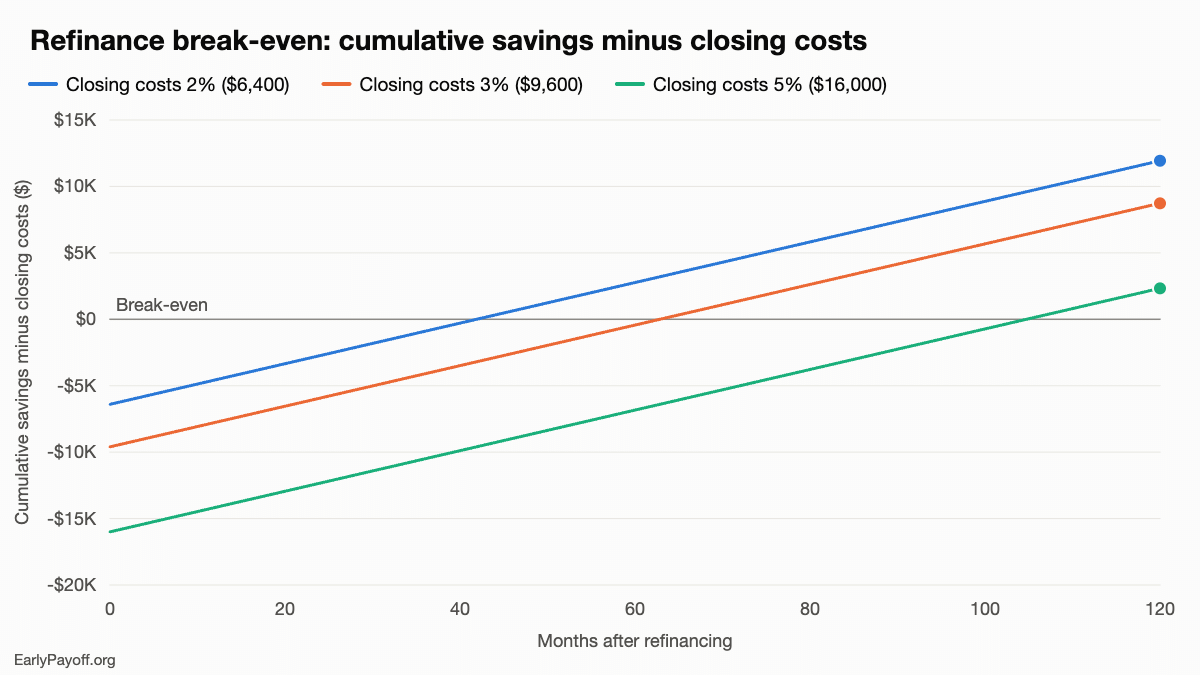
The chart shows cumulative payment savings minus closing costs. Each line starts below zero by the amount of the closing costs and crosses zero at the break-even month. The VA’s own refinance guidance recommends this same division of closing costs by monthly savings before you commit.
You may hear rules of thumb such as “only refinance if the rate drops by at least some fraction of a point.” Treat any such rule as a rough screen, not a fact. In this example the rate drops only 0.39 percentage point, yet the 2% scenario breaks even in 42 months. With 5% costs the same rate drop takes almost nine years to pay back. The cost, your timeline and the term you choose matter more than the size of the rate cut alone.
The “reset the clock” problem
The simple break-even math hides something. A new 30-year loan starts amortizing from scratch, so early payments are mostly interest and your balance falls more slowly than it would on the old loan. Our guide to reading an amortization schedule shows why. The table below compares total remaining interest under four choices, before closing costs.
| Option | Monthly P&I | Payments left | Total interest from today | Interest vs. keeping current loan |
|---|---|---|---|---|
| Keep current loan (7.79%) | $2,368.37 | 324 | $447,353.58 | — |
| New 30-year at 7.40% | $2,215.62 | 360 | $477,617.05 | +$30,263.47 |
| New 27-year at 7.40% (term matched) | $2,285.12 | 324 | $420,375.37 | −$26,978.21 |
| New 15-year at 6.71% | $2,824.62 | 180 | $188,431.04 | −$258,922.54 |
The new 30-year loan lowers the payment but costs $30,263.47 more in interest because it adds three years of payments. Measured by payment savings plus the difference in loan balances, minus closing costs, that gap matters: with 3% or 5% closing costs, the household in our example never pulls ahead of simply keeping its old loan over the 27 years it had left. The 2% scenario is ahead only from month 74 through month 205, then falls behind as the extra years of interest catch up.
A term-matched 27-year loan saves $83.25 a month and $26,978.21 in lifetime interest, but at 3% closing costs it takes about 115 months to recover them. Not every lender offers custom terms, so ask. Another option is to take the 30-year loan and keep paying the old $2,368.37. In the calculation, that pays the loan off in 292 months (24 years, 4 months) and saves $77,390.09 in interest versus keeping the old loan, or $70,990.09 after 2% closing costs. The 15-year loan saves the most interest but raises the payment by $456.25, which only works if your budget can absorb it.
Types of refinance
Rate-and-term refinance. You replace the loan to change the rate, the term or both, without taking meaningful cash out. Fannie Mae calls this a limited cash-out refinance. It is what the example above models.
Cash-out refinance. You borrow more than you owe and take the difference in cash. As of Fannie Mae’s Eligibility Matrix dated August 5, 2026, the maximum loan-to-value (LTV) for a cash-out refinance on a one-unit primary home with a fixed-rate loan is 80%, so you keep at least 20% equity. For smaller cash needs, compare a home equity line of credit; see what a HELOC is and how to apply.
FHA Streamline Refinance. HUD’s streamline program lets you refinance an existing FHA-insured loan with limited documentation and underwriting. The loan must be current, and the refinance must give you a “net tangible benefit,” which HUD defines by loan type and the new rate or term. You may not take more than $500 in cash, and FHA does not allow closing costs to be added to the new loan amount, though some lenders cover them through a higher rate.
VA Interest Rate Reduction Refinance Loan (IRRRL). If you already have a VA-backed loan, an IRRRL can lower your rate or move you from an adjustable to a fixed rate. You must be refinancing the existing VA loan and certify that you live or used to live in the home. As of October 2026, va.gov lists the funding fee for an IRRRL at 0.5%, compared with 2.15% (first use) or 3.3% (later use) for a VA cash-out refinance, and some veterans are exempt. VA allows IRRRL costs to be included in the new loan.
Refinancing to drop FHA mortgage insurance
Under HUD Mortgagee Letter 2013-04, FHA loans with case numbers assigned on or after June 3, 2013 carry annual mortgage insurance premium (MIP) for 11 years if the original LTV was 90% or less. If the original LTV was above 90%, which covers most minimum-down-payment FHA loans, MIP lasts for the full term. For those borrowers, refinancing into a conventional loan is often the only way to stop paying it.
Conventional loans handle private mortgage insurance (PMI) differently. Under the Homeowners Protection Act, as the CFPB explains, you can ask to cancel PMI once your balance is scheduled to reach 80% of the home’s original value, and the servicer generally must end it automatically at 78% if you are current. If your home has gained value, a conventional refinance at 80% LTV or below may avoid PMI entirely. Run the break-even math with the MIP you would stop paying added to the monthly savings.
| Refinance type | Who can use it | Cash out | Key rule to check |
|---|---|---|---|
| Rate-and-term (conventional) | Most borrowers who qualify | Limited | Lender credit, DTI and LTV requirements |
| Cash-out (conventional) | Owners with substantial equity | Yes | Max 80% LTV, one-unit primary home (Fannie Mae, Aug 2026) |
| FHA Streamline | Current FHA borrowers | No more than $500 | Net tangible benefit; costs cannot be added to loan |
| VA IRRRL | Current VA-loan borrowers | No | 0.5% funding fee unless exempt |
| FHA to conventional | FHA borrowers with enough equity | Optional | Removes FHA MIP; PMI applies above 80% LTV |
What lenders look at
Credit score. A higher score generally gets a lower rate and lower pricing adjustments. Minimum scores vary by loan program and lender, so ask each lender how your score affects the quote. Paying down card balances before you apply can help.
Debt-to-income ratio (DTI). This is your monthly debt payments divided by gross monthly income. As of October 2026, Fannie Mae’s Selling Guide sets a 50% maximum for loans run through its automated underwriting system, and 36% (up to 45% with qualifying credit and reserves) for manually underwritten loans. Individual lenders can be stricter.
Equity and LTV. LTV is the loan amount divided by the home’s value. More equity means more options and better pricing, and it determines whether you pay mortgage insurance. Appraisal. Most refinances need a current valuation; some streamline programs require less. If the appraisal comes in low, your LTV rises and the deal can change.
Risks to weigh
- Rolling closing costs into the loan. In our example, adding 3% costs ($9,600) to the balance shrinks the monthly saving to $86.29 and raises total interest on the new 30-year loan by $14,336.85.
- Extending the term. As the table above shows, a lower payment over more years can cost more in total.
- Cash-out for other debts. Paying off credit cards with home equity turns unsecured debt into debt secured by your house. If you fall behind, the home is at risk, and the balances can creep back.
- Adjustable-rate resets. An ARM’s rate equals an index plus a fixed margin after the initial period. The CFPB’s ARM handbook explains that periodic caps limit each adjustment and a lifetime cap limits the total increase; some loans allow a larger first change. Ask for all three caps in writing and calculate the payment at the lifetime cap.
- Prepayment penalty on your current loan. Under CFPB Regulation Z, a covered loan can carry a penalty only if it is a fixed-rate qualified mortgage that is not higher-priced, and only for three years: up to 2% of the amount prepaid in years one and two and 1% in year three. Older loans and some loan types may follow different terms, so check your note or ask your servicer.
How to refinance, step by step
1. Set your goal and timeline. Decide whether you want a lower payment, less total interest, a fixed rate, cash or no more mortgage insurance, and how long you expect to keep the home.
2. Apply with at least three lenders. Each must give you a Loan Estimate within three business days of your application. The CFPB notes that mortgage credit checks within 45 days count as a single inquiry, so shopping in a short window costs you little on your credit report.
3. Compare the Loan Estimates line by line. Ask for the same loan type and term from every lender. The CFPB’s Loan Estimate explainer suggests comparing origination charges on page 2 as a total, checking which services you can shop for, and using the APR and Total Interest Percentage on page 3. Our article on estimating and lowering closing costs covers how to push fees down.
4. Lock the rate. Once you choose a lender, a rate lock holds the quoted rate for a set period while the loan closes. See how to lock in a mortgage rate for lock lengths, extension fees and float-down options.
5. Close and check the numbers. Compare your Closing Disclosure with the Loan Estimate before signing, confirm that the old loan’s payoff is correct, and keep paying the old loan until the servicer confirms it has been paid off.
When refinancing is a bad idea
- You expect to sell or move before the break-even month.
- You are many years into your loan and would restart at 30 years just to get a lower payment.
- Closing costs are near the high end and the rate cut is small, as in our 5% scenario.
- You want cash out to cover spending that keeps recurring, such as credit cards you have not stopped using.
- Your current loan still has a prepayment penalty that wipes out the first years of savings.
- The offer swaps a fixed rate for an adjustable one you could not afford at its lifetime cap.
Frequently asked questions
How much lower does my rate need to be to refinance?
There is no fixed threshold. Divide your total closing costs by the monthly saving to get the break-even month, then compare that with how long you will keep the loan. Also compare the total interest of the new term with the years left on your current loan.
Will shopping several lenders hurt my credit score?
According to the CFPB, multiple mortgage credit checks within 45 days are recorded as a single inquiry. Getting all your Loan Estimates within a few weeks keeps the effect small.
Is a “no-closing-cost” refinance free?
No. The lender either adds the costs to your balance or charges a higher rate and uses the extra interest to pay them. HUD says this directly about FHA streamline refinances. It can still make sense if you may move soon, but compare it against the version where you pay costs upfront.
Can I refinance to get rid of FHA mortgage insurance?
Often, yes. If your FHA loan requires MIP for the full term, refinancing into a conventional loan with at least 20% equity can remove mortgage insurance entirely. With less equity you would pay PMI, which can be canceled later under the Homeowners Protection Act.
Should I refinance into a 15-year loan?
A 15-year loan usually has a lower rate and saves the most interest, but the payment is much higher. In our example it was $456.25 more per month than the current payment. If that would strain your budget, a longer loan with voluntary extra payments gives you flexibility.
Sources
- Mortgage Rates – Primary Mortgage Market Survey, Freddie Mac (and historical data file), accessed Oct 2026
- About PMMS, Freddie Mac, accessed Oct 2026
- Understanding the costs of refinancing, My Home by Freddie Mac, accessed Oct 2026
- Streamline Refinance Your Mortgage, HUD, accessed Oct 2026
- Mortgagee Letter 2013-04: Revision of FHA Annual MIP Policies, HUD, accessed Oct 2026
- Interest Rate Reduction Refinance Loan, U.S. Department of Veterans Affairs, accessed Oct 2026
- VA Funding Fee and Loan Closing Costs, U.S. Department of Veterans Affairs, accessed Oct 2026
- When can I remove private mortgage insurance (PMI) from my loan?, CFPB, accessed Oct 2026
- Eligibility Matrix (Aug 5, 2026), Fannie Mae, accessed Oct 2026
- B3-6-02, Debt-to-Income Ratios, Fannie Mae Selling Guide, accessed Oct 2026
- Consumer Handbook on Adjustable-Rate Mortgages, CFPB, accessed Oct 2026
- 12 CFR 1026.43 Minimum standards for transactions secured by a dwelling (Regulation Z), CFPB, accessed Oct 2026
- What is a prepayment penalty?, CFPB, accessed Oct 2026
- Loan Estimate explainer, CFPB, accessed Oct 2026
- What is a Loan Estimate?, CFPB, accessed Oct 2026
- What happens when a mortgage lender checks my credit?, CFPB, accessed Oct 2026
This article is general education, not individualized financial, tax or legal advice.